CASE STUDY
Designing a scalable client acquisition and account onboarding system
Overview
Product: RBC GoSmart - Direct Investing platform and InvestEase - Roboadvising platform
Scope: Targeted acquisition banners and value propositions, account selection screens and client suitability and regulatory screens within an onboarding flow
Role: Senior Content Designer
Impact areas: Faster task completion, higher account opens, scalable content systems, cross-team alignment
Project Stakeholders
Design team
Product designer
Content designer
Design researcher
Design manager
Partners and Stakeholders
Product owner
Business line partners
Engineers
Quality engineers
Compliance and legal partners
The problem
Create a digital acquisition and onboarding experience that offers speed and clarity whilst meeting young investors where they are.
Existing acquisition flow was:
Lengthy, with multiple suitability and regulatory questions that encouraged drop-offs and low account completion
Confusing financial terminology that didn’t clarify what the product value props were, didn’t provide the why of questions asked
No clear guidance on what users need to have to successfully complete the application
This led to:
Drop-offs during critical actions (choosing an account, choosing an investment portfolio, responding to regulatory questions)
Low trust in key financial moments
Co-creating throughout the design process
I focused on
Aligning product, design, and compliance
Creating clarity at critical decision points
Building scaleable content patterns
Product x Business
Aligned on which moments matter most
Prioritized high-impact flows (targeted value proposition banners and screens, account selection)
Aligned on measuring experience metrics that connect to product and business goals
Hypothesis
Design decision
Design x Research
Integrated into exploratory research: product canvas, journey maps
Aligned on how hypotheses and design decisions help determine experience metrics
Integrated content into interaction flows early
Shifted from “fill in copy later” to co-design
Did comprehension micro-testing and user testing
Metric
Tactic
My Approach
-
Product canvas
Discovery workshops
Assumption slam
-
Tree testing
Card sorting
Un-moderated A/B testing
The Design Process
-
Content design iterations
Accessibility copy
Business reviews Legal reviews
-
Content micro-testing
Microsoft Desirability toolkit
User comprehension and comparison testing
-
Ready for dev files
Content quality assurance
Accessibility QA testing
Platform metrics
DISCOVER
Business pain Points
High account rejections due to empty SIN = high drop-offs + high ops costs
High drop-offs at regulatory questions
High number of accounts not funded
Business goals
Improve conversion (flow completion rates)
Increase accounts opened and accounts funded
Increase trust in the platform for target users
DISCOVER
Constraints
Lack of real-time performance data
No graphs or real-time asset allocation and performance data
No ability to provide real-time timestamps
Balancing educational Content with Simplified Experience
Balancing educational content for early stage investors with simple experience that increased click-throughs and completion rates
Multiple account types with different rules (TFSA, RRSP, non-registered)
Strict legal, compliance and regulatory requirements on how and what information can be presented
Evolving but undefined brand voice
DISCOVER
Competitor analysis
WealthSimple, Questrade, Revolut, Coinbase, TD Invest, CIBC Investor’s Edge
Content audit
Existing account open copy decks
RBC Digital Style Guide
Existing content inventory
Existing user research and metrics
Existing personas and research
Platform data
Existing business and operational metrics
USERS
Users
GoSmart Direct Investing
Early stage investors (ESIs) with limited to no knowledge of investing and ETFs:
Between 18-35 years of age
Assets available for investing below $50,000
Either interested in buying securities recommended by friends, family and finfluencers
Or, overwhelmed by number of choices and want a simplified experience
InvestEase
Prefer hands off investing and primary investing strategy is set it and forget it
Price and fee conscious
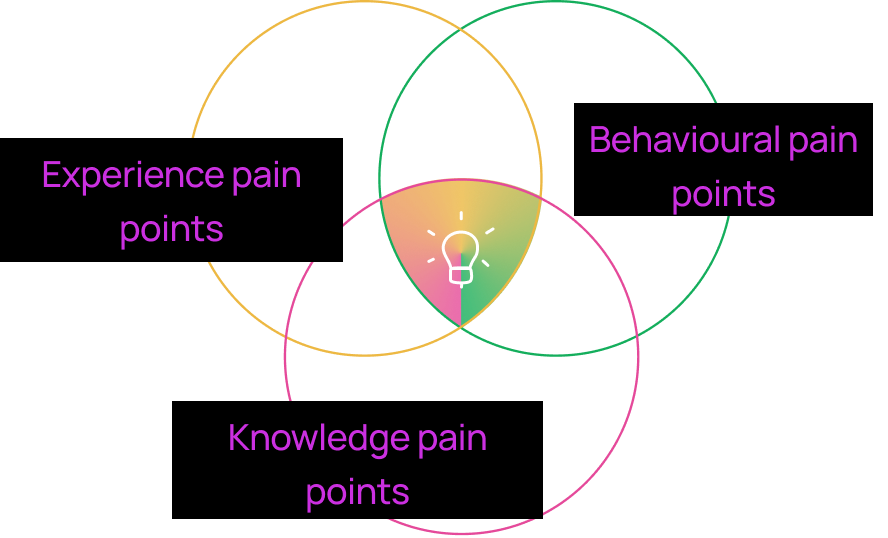
Pain points
Overwhelmed and uncertain
Feel overwhelmed by lack of financial knowledge and many options to choose from
Don’t know how to start or feel investing isn’t accessible and too expensive
Feel uncertainty where money is involved
Lack knowledge of account and investment types
Don’t understand the value proposition of the platform or investments and accounts within
Don’t understand the benefits of registered accounts
Don’t want to Answer So many questions at Onboarding
Don’t understand why we ask regulatory and suitability questions
Frustrations with understanding what terminology in some questions mean
Long onboarding flow with high drop-offs
User attributes
sub-groups based on needs and goals
Tax-free: Users looking to maximize tax benefits
“Grow your money tax-free”Quick and easy: Users looking to open an account quickly and with low fees and investable income
“Become an investor in under 60 seconds and get 50 free trades”Accessible: Users looking to invest in the pre-built portfolios
“Enjoy unlimited trades on select ETFs”Full control: Users wanting to control investment deposits
“Automate your investments while maintaining control”
DISCOVER
My Content Strategy
Simplify account onboarding
Focus on high utility copy, minimal education to reduce cognitive load.
Example:
When choosing an ETF, surface minimal data points needed to make an informed decision and keep copy low to reduce cognitive load
Use human-centered language
Translate financial/legal terms into digestible, human language without losing compliance.
Example:
“Beneficial ownership information” to “Personal information you’d like to share with companies in which you’ve invested”
Design for decision moments
Focus on high-impact points:
Choose an account
Choose an investment
Answer regulatory questions


Multiple copy iterations that balance the themes and value propositions that appeal to sub-groups of target users while also experimenting with a brand voice that pushes past the established norm.
Speaking to target sub-group of users who want full control over their investing but aren’t confident on where to begin
Version 1:
Real control is peace of mind.
Invest effortlessly on your terms. We’re here to make it easy.One tap, instant portfolio. Ready-made ETF bundles . Skip the guesswork. Just start.
Consistency > timing the market.
Set it once and let it go. Hit play or pause anytime. You’re always in control, even during dips.
Free trades? You got ‘em.
50 on North American equities. No commission fees to kill the vibes.
Transfer. Invest. Done. In real time.
Move money instantly. Catch market dips. Never miss a market opportunity.

Version 2:
You make the moves. We support the rest.
Always at your pace, always on your terms. Smart, simple ETFs.
Low cost, transparent. Build your own playlist of top stocks.
Set it once, let it go.
You’re always in control, hit play or pause anytime.
50 free trades = 50 smart moves
Try new moves, learn and grow. Your first 50 trades are on us.
Real time money moves = no delays.
Move money instantly. Market dips don’t wait. Neither should you.
Version 3:
Your money. Your moves.
Always on your terms. Invest your way.
Pick your playlists of stocks and ETFs you love.
Smart, simple investing.
Set it once and let it run. Pause, edit or hit play at any time.
Free trades where it counts.
Get 50 free trades on North American stocks and ETFs, on top of unlimited trades on select ETFs.
Deposit and invest. In real time.
Move money instantly. Never miss an opportunity.
Speaking to target sub-group of users who want Tax Free Investing
Version 1:
Hello, tax perks.
Reach your investment goals faster.Less taxes = big goals, faster.
TFSA, FHSA, RRSP —not just letters; they’re glow-ups for your goals.
Transfer and contribute. Instantly.
Move money in seconds. Contribute, pause, whenever. No missed deadlines, no over-contributing.
Free trades = more gains.
Your first 50 trades are on us. Keep more of your money invested.
Auto-invest, no stress.
Chill money moves on autopilot. Grow your TFSA, FHSA, RRSP without overthinking it.

Version 2:
Smart money starter pack.
Tax-smart investing made easy. Invest tax-free.
Did you know? Your RRSP, TFSA, and FHSA can hold stocks and ETFs —not just savings. Grow your money without extra tax slowing you down.
Less taxes = big goals, faster.
Use tax perks to save for a home, retirement, or anything bigger. Your investments do the heavy lifting.
Keep more invested.
Because your gains aren’t taxed the same way, more of your money stays in the market, compounding over time.
Auto-invest, no stress.
Invest on autopilot. Let your portfolio grow steadily, without overthinking it.
Version 3:
Tax benefits for big dreams.
Invest with your TFSA, FHSA, and RRSP — tax benefits built in. Gains on gains (on gains).
That’s compounding at work. Your money could earn, then those earnings earn, see the pattern?
Invest tax-free.
With TFSA or FHSA, your money grows tax-free. With RRSP, you get a break today and pay when you withdraw. Either way, you keep more.
Reach big goals.
Save for a home, retirement, or anything bigger — your investments do the heavy lifting.
Auto-invest with benefits.
Set recurring buys once and let the market do the work. Check in when you want.
Result
A fresh, clear, human-centered brand voice resonant with our target user group and targeted sub-groups with distinctive financial attitudes and value propositions.
WORK
Balancing brand identity with customer resonance
A fresh, new brand voice, but how far to go against RBC’s established brand identity?
Copy iterations grouped by themes and value propositions that appeal to the distinct user attributes of target sub-groups of users.
Here I created multiple copy iterations that balance the themes and value propositions most important to sub-groups of target users while also experimenting with multiple brand voices.
The result: a fresh, clear, human-centered brand voice resonant with our target user group and targeted sub-groups with distinctive financial attitudes and value propositions.
A fresh, new brand voice, but how far to go against RBC’s established brand identity?
The challenge: Balancing evolving brand guidelines and market positioning against the established brand identity and tone of voice of RBC.
The approach: Copy iterations grouped by themes and value propositions that appeal to the distinct user attributes of target sub-groups of users.
The result: a fresh, clear, human-centered brand voice resonant with our target user group and targeted sub-groups with distinctive financial attitudes and value propositions.
Simplifying complex information
Beneficial ownership what? Majority shareholder who?
A scenario that doesn’t apply to over 80% of target users. Mired in complexity. An uphill battle with compliance, legal and risk.
Fighting the good fight to simplify complex information to get to the heart of what’s important for our users:
Improving understanding of information presented through human-centered language;
Easy to choose the right option for their situation;
Reducing time on page and to continue to the next screen
The result: Simplifying user comprehension of complex information feeds into the primary goal for this flow — open an account in seconds
Creating positive friction
Balancing the requirements and obligations under OSC audit with the financial responsibility towards users to improve our recommendations to customers.
Investment recommendations that are relevant and responsible for user goals and financial situations vs. requirements and obligations of OSC audit.
The result: purposely dramatic copy to invoke market uncertainty, shareholder loss and evoke an emotional reaction and get an accurate picture of emotional risk tolerance.
Introducing positive friction in order of options from risk tolerant to risk averse to encourage customers to pause before selection and to reduce primacy bias..
Interested in having me speak?
Investment recommendations that are relevant and responsible for user goals and financial situations vs. requirements and obligations of OSC audit.


Descriptive and contextualized options.
Sequence from risk tolerant to risk averse to reduce primacy effect and to increase friction.
Result
Push users to think through and choose an option instead of the first as default and get an accurate picture of emotional risk tolerance.